Ahrefs Domain Rating set in type 25 Oct 2026, reset 25 Oct 2026.
MedDebt Calculator metrics
Set in type for medschooldebtcalculator.com: Ahrefs Domain Rating and Majestic link data, with the change since the last edition.
Metric
Value
Domain Rating
3● no change since last check
Trust Flow
1● no change since last check
Citation Flow
26● no change since last check
Referring domains
22● no change since last check
External backlinks
103● no change since last check
Ahrefs Domain Rating set in type 25 Oct 2026, reset 25 Oct 2026. Lead topic: Arts/Performing Arts (1). Majestic set 25 Oct 2026, reset 25 Oct 2026. Link data typeset by Majestic. Trust Flow, Citation Flow and Topical Trust Flow are trademarks of Majestic-12 Ltd.
MedDebt Calculator domain colophon
From the registry's public RDAP record, checked 25 Oct 2026, 02:50 UTC.
A free, browser-based calculator that models medical school debt repayment strategies with 21 specialty presets, comparing PSLF, refinancing, and aggressive
The story so far
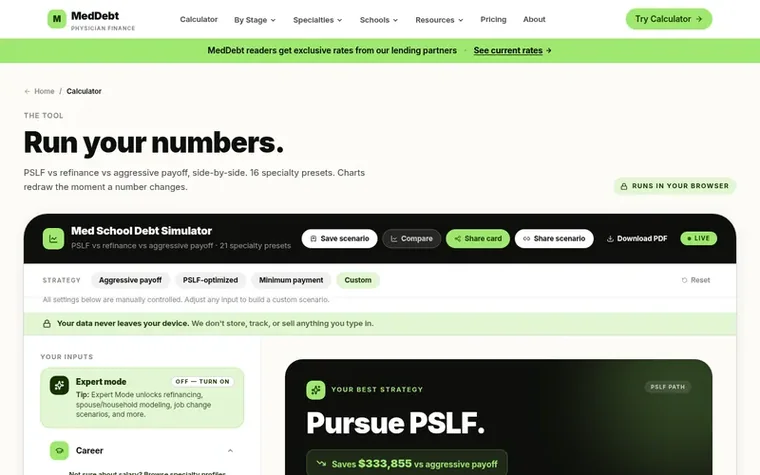
Homepage of MedDebt Calculator
MedDebt Calculator is an independent, free debt-planning tool for medical students, residents, and attending physicians. It runs entirely in your browser, comparing three repayment strategies side-by-side: PSLF (Public Service Loan Forgiveness), refinancing to private loans, and aggressive payoff. The calculator includes 21 specialty presets with attending salaries and residency lengths, models income-driven repayment plans, projects loan balances and net worth year-by-year, and tracks progress toward 120 qualifying PSLF payments. All data stays on your device—nothing is stored, tracked, or sold. The tool is free and always will be; a paid Pro tier adds automated PSLF tracking, policy alerts, and unlimited AI questions.
Typeset features
PSLF vs refinance vs aggressive payoff comparison
21 specialty presets with salary and residency data
Real-time chart updates as inputs change
PSLF payment tracker (120 qualifying payments)
Expert mode for spouse modeling and job change scenarios
Disability coverage gap calculator link (MedDisabilityCalc)
Pricing
Pricing model: Freemium
Free tier: full calculator, all 21 specialty presets, strategy comparison, 3 saved scenarios, 15 AI Co-Pilot questions per day. Pro: $29/month or $199/year (save $150 annually)—adds PSLF payment tracker with reminders, refinancing window alerts, policy change alerts, unlimited scenarios, unlimited A
According to the AAMC 2024 Graduation Questionnaire, the average medical school debt at graduation is $202,450, with 73% of MD graduates carrying federal student debt. Debt varies by specialty: primary care physicians average $198,000–$213,000 while surgical subspecialists average $237,000–$258,000. By the end of residency, balances are typically 15–25% higher due to interest accrual at 8.08% on unsubsidized loans.
Should I pursue PSLF or pay off my medical school loans aggressively?
PSLF is generally better for primary care physicians (family medicine, pediatrics, internal medicine, psychiatry) working at nonprofit hospitals or academic medical centers, where PSLF can save $80,000–$150,000 compared to aggressive payoff. Aggressive payoff is better for high-earning surgical subspecialists (neurosurgery, orthopedics) at for-profit employers, where a low debt-to-income ratio makes rapid paydown practical. The MedDebt Calculator compares both side-by-side with your exact numbers.
How much do medical school loans cost during residency?
At the current unsubsidized graduate loan rate of 8.08%, a $202,450 balance accrues roughly $16,358 in interest per year. Over a 3-year residency (family medicine, emergency medicine) that is approximately $50,900 in unpaid interest. Over a 5-year residency (general surgery, radiology) that is approximately $101,800. This accrued interest capitalizes when repayment begins, permanently increasing the principal balance.
What is the best IDR plan for physicians in 2026?
As of 2026, IBR (Income-Based Repayment) is the recommended IDR plan for most physicians pursuing PSLF. The SAVE plan was eliminated by the 8th Circuit on March 10, 2026, and PAYE/ICR are phased out for new enrollees after July 1, 2026. For loans disbursed on or after July 1, 2026, RAP (Repayment Assistance Plan) is required. IBR caps payments at 10% of discretionary income for post-July 2014 borrowers and provides PSLF-qualifying payments.
Should I refinance my medical school loans during residency?
No—refinancing during residency is almost never the right move. Refinancing converts federal loans to private, permanently eliminating access to PSLF, IBR, and federal forbearance. This removes your safety net during years when income is lowest and financial obligations are highest.
Leave a review for MedDebt Calculator
No review of MedDebt Calculator set in type yet. Set the first.
 AstroCalcolo
 TDEE Calculator
 TidyUse